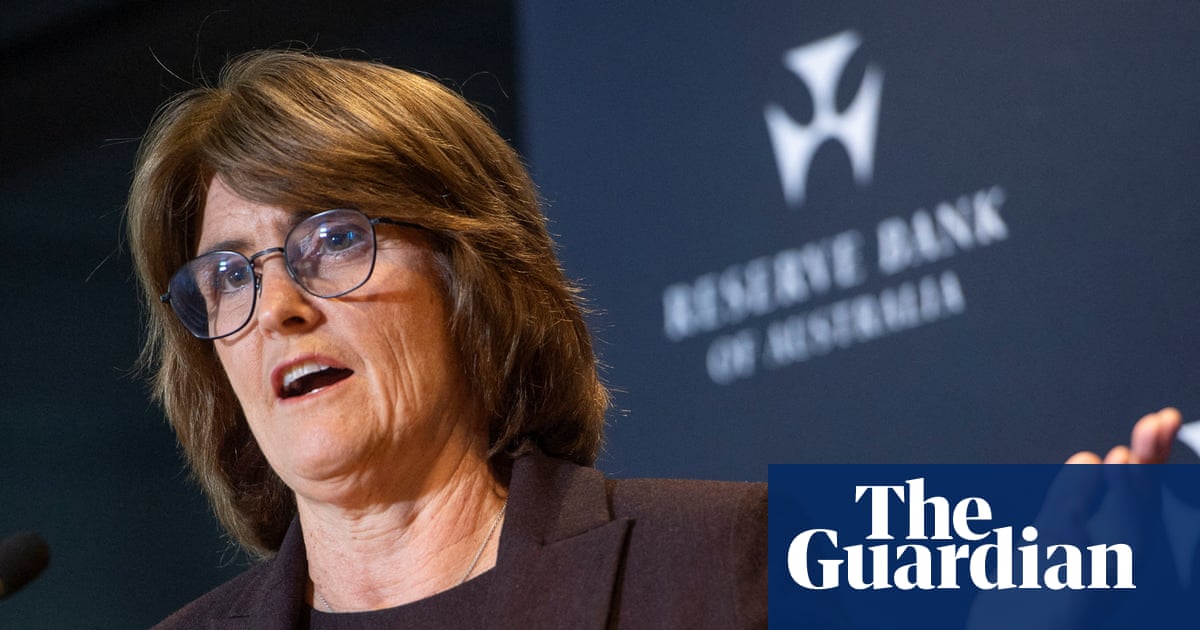
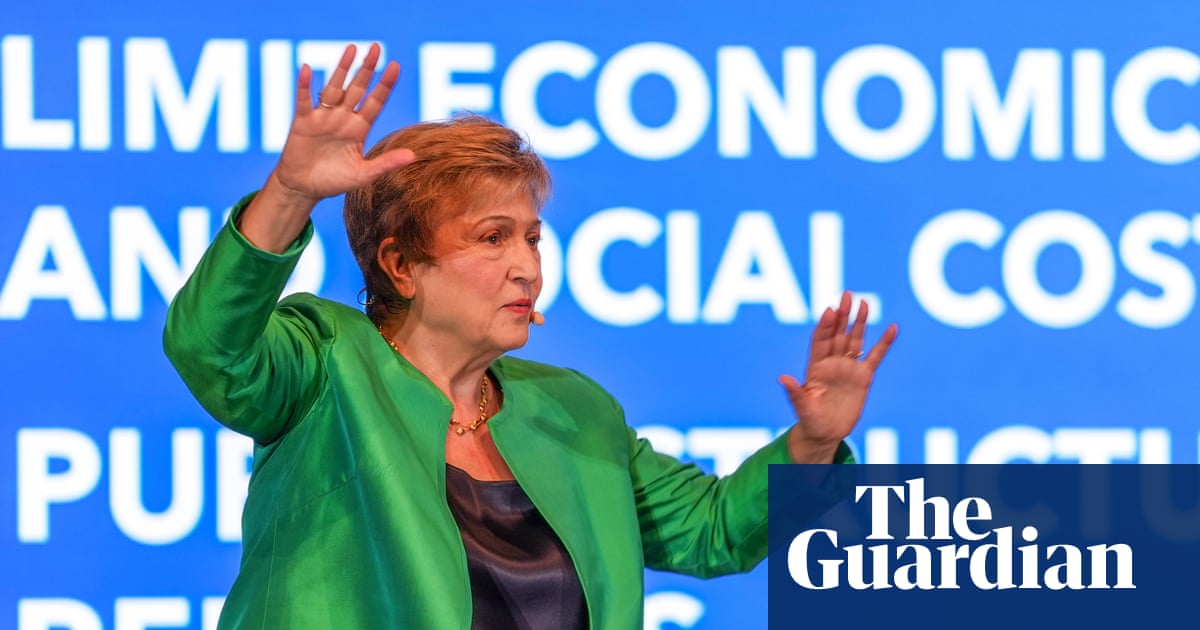
The head of the International Monetary Fund (IMF), Kristalina Georgieva, has called on governments in major economies to tighten their belts as soaring bond yields impact budgets. Speaking in Singapore, Georgieva highlighted that global debt-to-GDP ratios are at their highest level since World War II and are projected to reach 100% in the coming years.
Urgent Policy Action Needed
Georgieva emphasized that governments cannot depend on rapid economic growth to alleviate the burden of debt. Instead, she stated they must make "very tough political choices." Her remarks came ahead of the upcoming IMF and World Bank annual meetings scheduled to take place in Bangkok next week.
“"My message to the world’s economic policymakers will be this: we cannot keep delaying necessary policy action – you have the tools, now have the wisdom to use them," Georgieva said.
She expressed concern over the lack of decisive action in high-debt advanced economies, where credible medium-term fiscal consolidation plans are urgently needed, sometimes supported by upfront fiscal measures.
Rising Bond Yields
In recent weeks, bond yields, which represent the interest rate on debt, have surged, increasing borrowing costs for many governments to multi-decade highs. This rise is attributed to market adjustments in response to higher inflation expectations due to the ongoing war in the Middle East.